
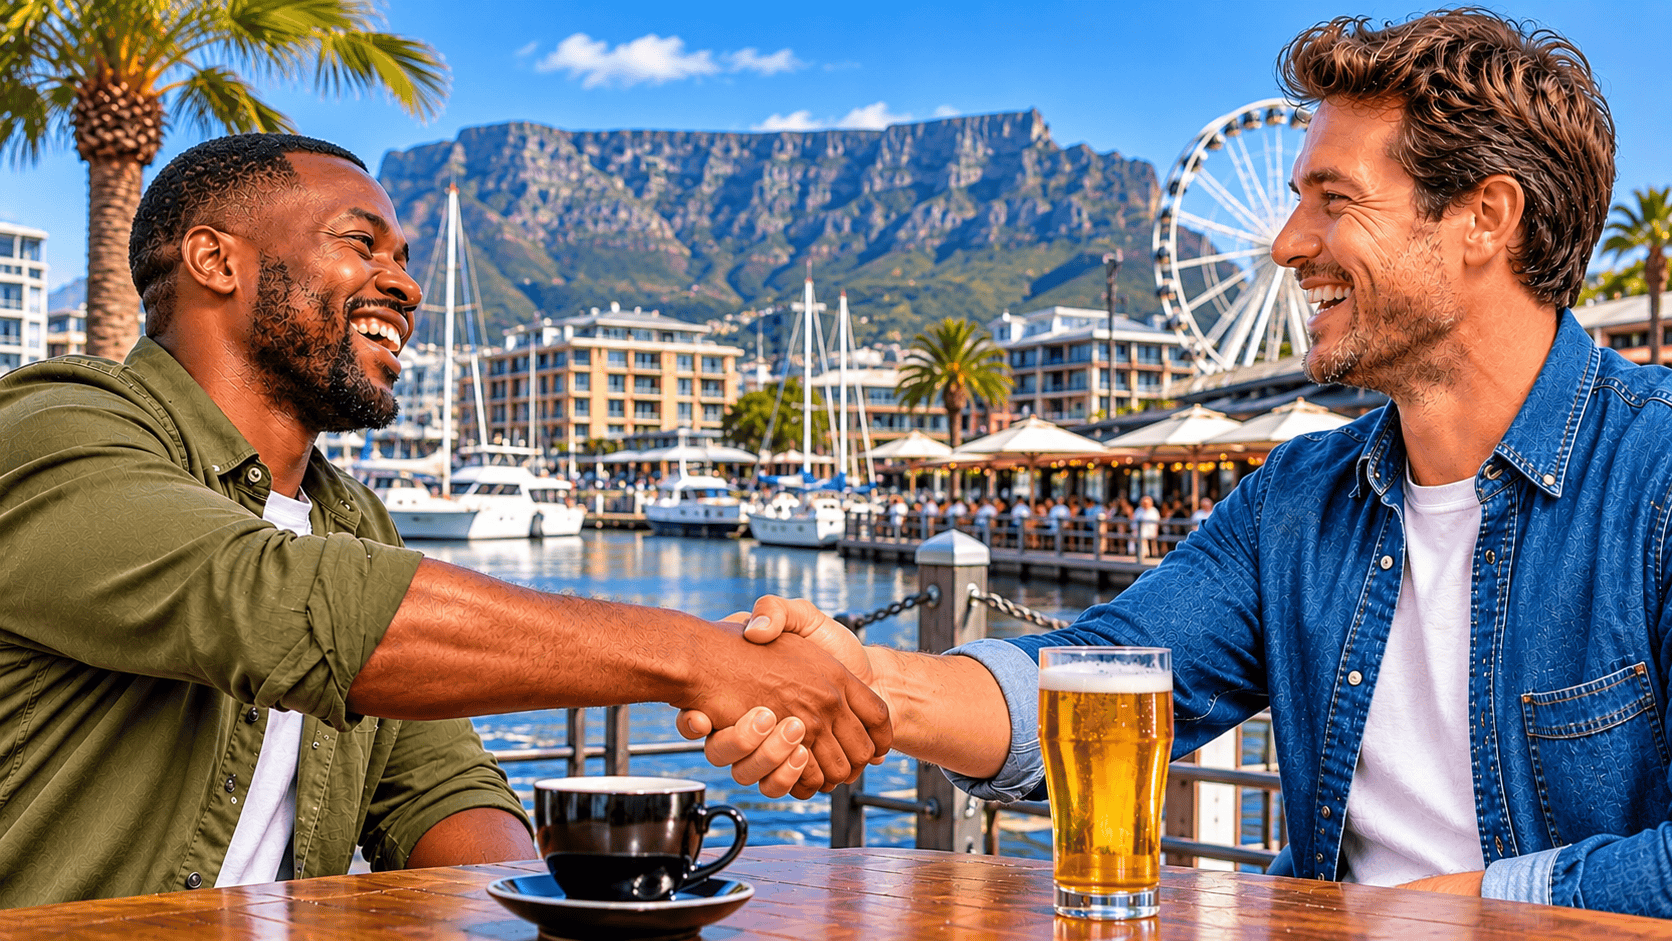
Ever sealed a deal with a firm handshake, a nod, and a “cool, let’s do it”? In South Africa, that quick chat over coffee or a beer might have just legally bound you to a contract—no ink, paper, or signatures required.
Under our common law, verbal contracts are generally valid for everyday transactions, such as buying furniture, paying someone to do repairs or purchasing a second-hand vehicle. As long as both parties agree on the essential terms and the other legal requirements for a valid contract are met, the agreement can be enforceable.
But there is a catch: if a disagreement arises later, proving exactly what was agreed can become difficult and expensive. Without a written agreement, it may come down to what each person remembers, what witnesses can confirm and what other evidence is available, such as WhatsApp messages or proof of payment.
However, there are certain transactions where the law specifically requires a written agreement. Buying or selling a property is one of them.
Under the Alienation of Land Act 68 of 1981, an agreement to buy or sell immovable property, such as a house, apartment or piece of land, must be recorded in a written deed of alienation and signed by the parties, or by agents acting with their written authority.
A verbal agreement to sell property is therefore generally invalid and cannot be enforced as a valid sale. The Act does contain a limited exception where the purchaser has performed fully in terms of the agreement and the property has also been transferred to the purchaser.
This is why putting an agreement in writing is so important. A properly drafted contract records what both parties have agreed to, helps prevent misunderstandings and provides evidence if a dispute arises later.
When payment is spread over time, there are also different ways to structure a transaction. The right arrangement depends on what is being bought, how payment will work and how much protection each party needs.
1. Instalment Sales (Paying Over Time)
An instalment sale allows a buyer to purchase an item and pay for it over an agreed period instead of paying the full amount upfront.
This is commonly used when buying expensive items such as motor vehicles, furniture or equipment.
Depending on the agreement, the buyer may receive and use the item immediately, while ownership only passes once the full purchase price has been paid.
The contract may include a retention of ownership clause, which means the seller keeps ownership until the buyer has settled the outstanding amount.
For example, someone buys a vehicle on an instalment agreement. They can take the vehicle home and use it, but the agreement may provide that ownership only transfers once all the required payments have been made.
There are important considerations:
- Seller’s risk: The seller may remain the legal owner while the buyer has possession and use of the item. The seller therefore faces risks if the item is damaged, disposed of or not properly maintained.
- Consumer protection: Certain instalment sales fall under the National Credit Act 34 of 2005 (NCA). However, not every private instalment arrangement automatically qualifies as a regulated credit agreement.
- Missed payments: Where the NCA applies, the credit provider must follow the required legal procedures before enforcing the agreement or repossessing the goods. This includes the applicable notice requirements and, where necessary, obtaining a court order.
The NCA also gives consumers certain rights if they can no longer afford the payments, including procedures for voluntarily surrendering goods under specific circumstances.
2. Staged Sales and Suspensive Conditions
In larger commercial transactions, such as buying shares in a company or acquiring business assets, buyers and sellers sometimes agree to structure the transaction in stages rather than completing everything immediately.
A staged sale (also called a tranche sale) allows the parties to agree that portions of the purchase price, shares or assets will be transferred at different stages, depending on what the contract provides.
For example, a buyer may agree to purchase a company’s shares in three separate stages, with each portion being transferred once the relevant payment or other agreed requirements have been met.
A commercial agreement can include several protections:
- Staged transfers: Shares or assets are transferred in agreed portions as the buyer meets specific payment milestones.
- Suspensive conditions: Certain contractual obligations only become operative once specified conditions have been fulfilled. These could include obtaining finance, receiving regulatory approval or securing the necessary consent from another party.
- Seller protection: The contract can include restrictions on selling or transferring assets to someone else, security arrangements and other safeguards to protect the seller against non-payment.
- Default provisions: The agreement can explain what happens if the buyer fails to make payments, including the seller’s rights to enforce the agreement or cancel it where legally permitted.
It is important to understand that a suspensive condition does not automatically mean that ownership or control remains with the seller until the final payment has been made. This must be clearly addressed in the contract.
When company shares are involved, the Companies Act 71 of 2008 and the company’s Memorandum of Incorporation must also be considered, particularly when dealing with the transfer and registration of shares.
Why Getting It in Writing Matters
Whether you are buying a second-hand vehicle, paying for building work, purchasing business assets or entering into a major commercial transaction, understanding exactly what you are agreeing to is essential.
Although many verbal agreements are legally binding in South Africa, they can be difficult to prove when things go wrong. In certain transactions, such as the sale of immovable property, written agreements are a legal requirement.
A properly drafted agreement should clearly explain:
- What is being bought or sold.
- The agreed purchase price and payment arrangements.
- When ownership and possession will transfer.
- What happens if either party fails to meet their obligations.
- How disputes, cancellations and defaults will be handled.
The National Credit Act, the Alienation of Land Act and other applicable legislation can significantly affect your rights and obligations.
The bottom line: A handshake can create a legally binding agreement in South Africa, but it is not always enough. Putting the agreement in writing and having it checked by a legal professional can help protect both parties and prevent costly disputes later.
Contact us to lock in your deals. We draft legally watertight sales contracts designed to safeguard your business.

Recent Comments